

This article is a part of Poland Unpacked. Weekly intelligence for decision-makers
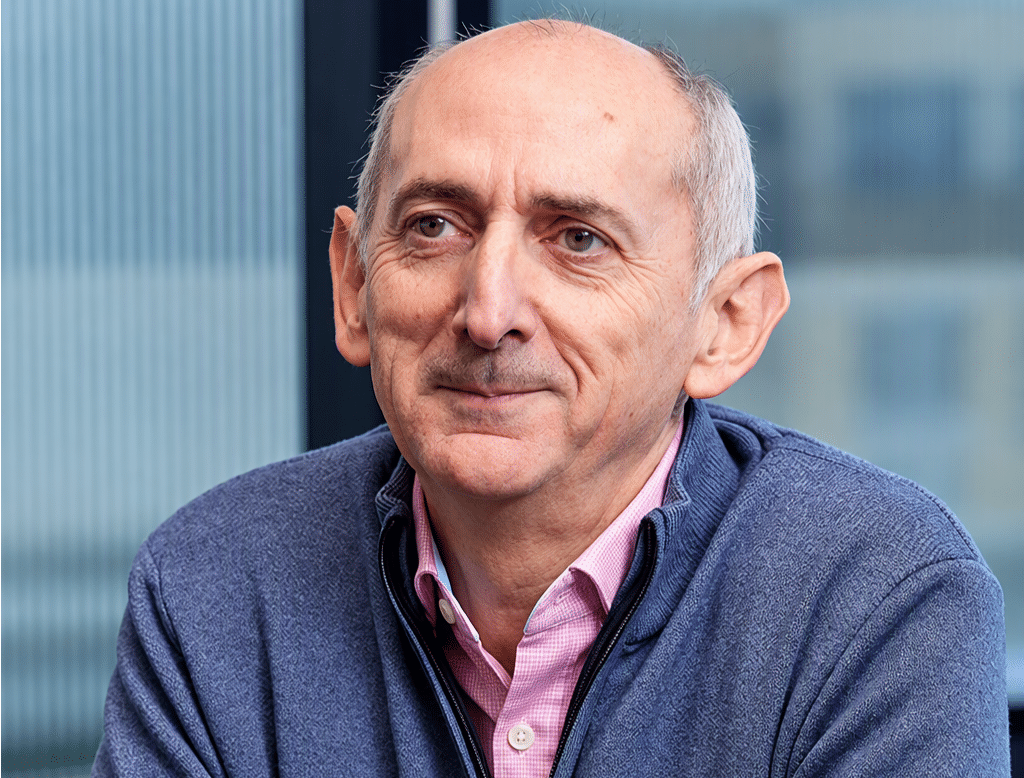
Expansion into new markets, acquisitions of competitors and even the purchase of a bank. Following a change of ownership, Britain’s International Personal Finance (IPF), the owner of Poland’s Provident, wants to accelerate its growth. “We will not run short of funds,” says Gerard Ryan, IPF’s chief executive.
Nearly two months ago, on August 4, US fund BasePoint Capital completed its acquisition of International Personal Finance (IPF), the owner of Poland’s Provident, which also operates lending businesses in countries including Romania, Mexico and Australia. In his only interview with Polish media, Gerard Ryan, IPF’s chief executive, explains how the ownership change and the company’s delisting are affecting the business. He also signals further significant changes.
Piotr Sobolewski, XYZ: Does it feel different?
Gerard Ryan, chief executive of IPF, the owner of Provident: It feels the same. Everyone expects that because we have changed ownership, we will now face sudden changes. That is not how it works. Until August 4, we were listed on the UK stock exchange and had thousands of shareholders. We have now replaced those thousands with one — BasePoint Capital.
It is a private-equity fund, and the standard strategy for such investors is to scale up the business, reduce costs and usually exit after several years, once the company is worth significantly more than when they acquired it.
Who's who
A manager who has led a lending business for almost 15 years
Gerard Ryan has headed International Personal Finance since the beginning of 2012. During that time, he developed the group’s second business arm by acquiring MCB and using it as the basis for IPF Digital, an online lender complementing the traditional model of selling loans in customers’ homes. At the same time, he accelerated the group’s growth in Mexico and expanded its offer to include credit cards.
Before joining IPF, Ryan worked at Citi in London and spent three and a half years as chief executive of GE Money Bank in Czechia.
IPF’s new owner wants to accelerate the group’s growth
So should we expect another ownership change in five years?
If you look at BasePoint’s business, it seems somewhat different. They buy a significantly undervalued business in a sector they believe in and invest in it for the long term. Our organisation currently operates in 10 countries and employs a total of 20,000 people. BasePoint, meanwhile, has 110 employees managing multiple investments.
That means they did not acquire us in order to run our operations themselves, but rather to support the management team in executing the strategy faster and more effectively.
At the same time, now that you are no longer listed, you will not have to keep meeting investors and analysts. Is that a relief?
When we were listed, we spoke to investors practically every three months. We would discuss quarterly results, and to some extent our perspective was short-term because every quarter required us to present an updated story and fresh achievements. That had a significant impact on the organisation’s decision-making process.
Now we will no longer have to do that. BasePoint wants us to increase the scale and value of the business over time, but it does not need to scrutinise our performance in detail every few weeks.
Organic growth, expansion and acquisitions are all on the table
Which metrics will the new owners judge you on?
Above all, execution of the strategy, just as before the takeover. We have a strategy called NextGen, built on three pillars: creating products that increase financial inclusion, improving organisational efficiency, and investing in technology and data. That strategy remains in place.
When it comes to accelerating growth, however, we will look at three areas. First, how to speed up organic growth in the markets where we are already present. Second, we will consider entering additional countries. The third area is potential acquisitions.
What will determine your choice of new markets?
We stick to the principle that we serve countries with a high proportion of unbanked or underbanked people, where there is room for companies like ours. The rule of law matters to us because we do not want to enter markets that resemble the Wild West. We also consider the effectiveness of the court system, the ability to recover debts in cases of non-payment and transparent regulations that create a level playing field for all market participants.
We also look at exchange-rate volatility and GDP per capita, because these indicate how much we can lend to consumers. Peru is an example. We looked at the market many years ago. There are many underbanked customers there, but GDP per capita was low enough that we could not build a business model in which the value of the loans would cover the cost of maintaining the infrastructure. All these conditions have to be met before we decide to enter a market.
IPF sees risks in expanding into Africa and China
Which markets definitely fail those tests, and which might pass them?
In our case, it is already too late to enter Africa. Sending money between users by phone is genuinely easy there, so entering the market with a lending offer through traditional distribution channels might not be attractive to consumers. In addition, insufficient regulation in some countries could make debt recovery more difficult.
Some people advise us to enter China: even a 1% share of such an enormous market would significantly increase the scale of our business. But without a local partner, that would involve substantial cultural and business risks.
As for attractive destinations, I would point first to countries neighbouring the markets where we are already present. Latin America is also interesting, for example Colombia, Ecuador and Costa Rica. In fact, almost any market could be attractive if we were able to enter it by acquiring an existing player.
CCD2 could trigger major changes in Poland
What about acquisitions?
I think that in the near future we will see considerable change in many markets, especially Poland, driven by regulation. The market will become increasingly difficult because profitability may become unacceptable to some investors. As a result, some players will begin looking for opportunities to exit. I can already see companies considering such a scenario.
To be clear: we are not considering such a move ourselves. But we will watch our competitors and look for opportunities to grow our business if conditions become too difficult for others.
So you will make acquisitions in Poland?
I am not saying that. But after CCD2 [the Consumer Credit Directive — ed.] is implemented, we will certainly see major changes in the Polish market.
Would potential acquisitions be aimed at increasing scale or rather at entering new niches?
We will not look for businesses specialising in loans sold in customers’ homes because we are already the largest player in that segment. We are more likely to focus on online lending, including financing for small and medium-sized enterprises. We are in a unique position here because one of BasePoint’s key areas of expertise in the US is precisely financing smaller businesses.
IPF chief sees customers’ borrowing needs changing
What about popular niches such as buy now, pay later and merchant cash advances?
Let us return to our strategy, which is about financial inclusion. If such solutions can help us achieve that, we should consider them. We can see how customer behaviour is changing. People want financing that is faster and simpler, preferably without leaving home.
We often hear that you simply have to be present in BNPL and help customers finance purchases. But that requires the right capabilities — either acquired through takeovers or developed internally.
Isn’t it too late? Poland already has Allegro Pay, Klarna, PayPo, Twisto and BLIK in this market.
It is later than it should be, but it is never too late. Especially because we are talking about a somewhat different proposition. The market is dominated by short-term financing. We, by contrast, have experience that allows us to extend repayment periods and could do so more efficiently than our competitors.
When might a decision be made to enter this segment?
When it happens, people will certainly hear about it.
“Scale matters in consumer lending”
In May, IPF acquired Czech lender Express Cash. What is your acquisition strategy? Are there businesses that are too small or too large to be on your radar?
That was an acquisition of a company specialising in agent-led sales. You have to understand that scale matters in consumer lending. If you do not achieve it, you will never reach the satisfactory profitability investors expect.
I think, however, that the organisational culture of a business for sale matters more than its size. When we acquire a company, it is important that it operates according to principles similar to ours. In recent quarters, we have looked at businesses that appeared attractive from the outside, but when I spoke to their employees, I could see that the two organisations operated in very different ways.
But after an acquisition, you can change the management style…
You can, but if the team has worked in a certain way for years, such a change would be fundamental. That means a high risk of integration failure.
How much money do you have for acquisitions?
We are one of the most conservative players in our industry. Around 50% of our loan portfolio is financed with equity. That means we can allocate more to acquisitions than our competitors because our balance sheet is genuinely conservative. We will not run short of funds.
Provident Bank? A banking licence could be useful
Then why limit yourselves? Would it not make most sense to acquire a bank, given that regulations for non-bank lenders increasingly resemble banking regulations?
I like the idea of having a bank in our group. A few years ago, I was against it. I thought it was too complicated and that the sector was overregulated.
Now, however, we ourselves are regulated almost like banks. We face similar burdens, we pay the bank tax, while banks fund themselves much more cheaply because they can accept customer deposits. They also have mechanisms that help them run their business, such as bad-debt relief. So we are looking around because a banking licence could be a useful element of our overall strategy.
Are we talking about acquiring a large bank?
We would certainly be interested in an institution in the European Union, but rather a small one. We want a bank that would fit into our group and would not dominate it. We do not want the entire organisation to become a bank.
What would it give you beyond lower funding costs?
It would change how we are perceived. Non-bank institutions often have lower status in the market and a worse image. I believe that if we had a banking licence, consumers and other stakeholders would begin to see us differently.
Our people do a great deal to promote financial inclusion, and if a banking licence can help with that, we will make use of the opportunity.
EU countries are implementing CCD2 differently
Let us return to regulation. Individual member states are implementing the second Consumer Credit Directive, CCD2. How do you assess the process?
The idea behind the regulation was to create the same rules of the game for all market participants across the European Union, which was supposed to improve the offer for customers. Instead, we are seeing individual countries implement the directive in different ways.
Hungary has already done so, and its rules are relatively close to the directive itself. Other countries, however, are adding a range of provisions reflecting the specifics of their local markets.
For us, this creates significant regulatory complexity and means having to adapt in each country under somewhat different rules. That requires substantial investment.
In Poland, we do not even know the final shape of the new regulations yet, even though the deadline for implementing the directive falls in November. We cannot prepare systems and processes if we do not know which rules will apply.
Are you not tired of this regulatory uncertainty? Would it not be better to focus on markets where margins are higher? Your Mexican business, for example, is growing quite quickly.
I still believe in Europe. Mexico has 120m people and an enormous group who remain outside the banking system and need financing. So we have plenty of opportunities there, but they also come with significant additional risks, including high loss rates and cultural differences.
For example, people there may change their phone numbers every few months. In an industry where maintaining contact with customers is crucial, that is a serious problem.
In Europe, we do indeed have more regulation and more competition, but risk is lower. What is more, if we operate according to market rules and remain efficient, we can still achieve reasonable returns on capital.
Regulation has made the Polish team highly innovative
What will your strategy in Europe be? Do you want to be the leader in every market, or is market position not that important?
Sometimes it is better to be the leader because regulators drafting the rules take your opinion into account. You can then have more influence over the regulatory environment.
On the other hand, when politicians decide for various reasons to criticise a sector, the market leader usually takes the hardest hit.
I ask because in Poland you have fallen behind Smartney in terms of portfolio size.
I like our Polish business very much, but regulation is making it increasingly difficult. That, in turn, has affected our market position.
We are becoming an increasingly heavily regulated business, but I try to see the positive side in situations like this as well. This is one of them.
This environment has made the Polish team the most innovative in the entire group. Solutions developed in Poland are subsequently rolled out in other IPF markets.
One example is credit cards, which we are now launching in Romania using our Polish national payment institution licence. We expect strong growth there, although probably slower than in Poland.
Despite digital growth, agent-led sales will remain
You have issued 230,000 cards in Poland so far, meaning that 70% of customers with a Provident loan use one. Isn’t it time to look for customers beyond your existing base?
Our customer base will always be the most important because these are people we know and who already trust us.
When selling credit cards outside our own base, we have to persuade people we are meeting for the first time to use the product, while also assessing their financial capacity and needs.
What about loan-distribution channels? Will you abandon traditional home-credit loans in favour of online channels?
Ten years ago, people were already asking me whether agent-led lending would survive. Then, as now, I said it would do well.
In every economy where we operate, there are customers who cannot or do not want to use online loans. Sometimes they lack sufficient digital skills or a sufficiently developed digital footprint. At other times, they simply do not trust technology or banks.
Agent-led sales, by contrast, allow us to build trust and a long-term relationship with customers. That means we can approve as many as 65–80% of the loan applications we receive. Online, that share falls to 35–40%.
That shows how important direct contact with the customer remains. Some agents are even more conservative than the institution itself — they prefer to lend a customer slightly less in order to reduce the risk of repayment problems.
How many agents do you have?
Around 16,000 globally. Their number has fallen because more customers have moved to digital channels. But the relationship between an agent and a customer is still difficult to replace. That is why agents will remain an important channel for our business.


Key Takeaways
- IPF’s new owner is expected to accelerate the group’s growth. Following its delisting, the company no longer operates under the same pressure to deliver quarterly results. BasePoint Capital expects the value of the business to increase over the longer term, while IPF wants to accelerate organic growth, international expansion and acquisitions.
- Regulation could trigger a shake-up in Poland’s lending market. IPF expects some companies to struggle to maintain acceptable profitability and potentially seek an exit. The group says it has the resources for acquisitions and is also considering buying a small bank in the EU, which could lower funding costs and change how the group is perceived.
- Digitalisation does not mean the end of agent-led sales. Poland is an important testing ground for new IPF products, including credit cards that are subsequently rolled out in other countries. At the same time, the group intends to retain its traditional agent channel because direct contact with customers allows it to approve a higher share of applications than online channels.